
Billionaire businessman and Chairman of First HoldCo Plc, Femi Otedola, has commended President Bola Tinubu’s economic reforms, saying they have positioned Nigeria for sustainable growth.
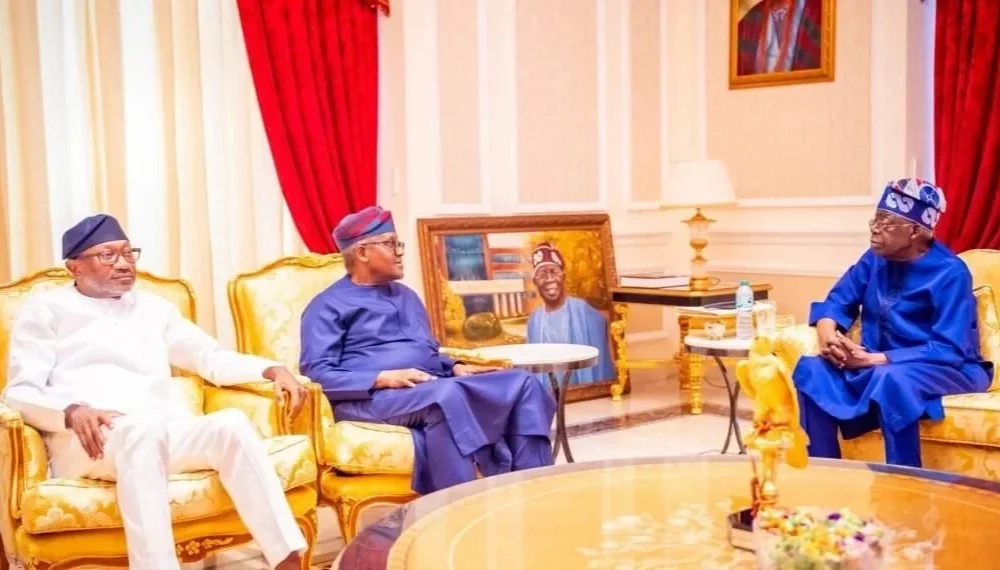
Otedola spoke after a private dinner with Tinubu in Paris, France, on Monday evening, according to a post he shared on Tuesday.
The First HoldCo chairman cited developments in Nigeria’s capital market, foreign exchange market, external reserves and investment environment as signs that the reforms were producing results.
“At a private dinner in Paris yesterday evening with His Excellency, President Asiwaju Bola Ahmed Tinubu, whose bold and forward-thinking reforms have put our economy firmly on a path of sustainable growth,” Otedola said.
He added that the effects of the reforms were becoming increasingly visible, citing Nigeria’s return to the FTSE Russell Frontier Market classification, the performance of the Nigerian Exchange and stronger external reserves.
“The results are increasingly evident: top Nigerian companies now included on the FTSE Russell Frontier 50 Index, the NGX at historic highs, increased foreign direct investment and renewed economic confidence, a unified and more stable foreign exchange market, foreign reserves standing strong at about $55 billion, and so much more,” he said.
“I remain proud of you, Mr. President!”
READ ALSO; Otedola eyes majority control of First HoldCo, targets 51% stake
Otedola’s comments followed Nigeria’s return to FTSE Russell’s Frontier Market classification after a three-year absence. Six Nigerian companies—FirstHoldCo, Zenith Bank, Guaranty Trust Holding Company, Dangote Cement, Aradel Holdings and MTN Nigeria—were included in the FTSE Frontier 50 Index, with the revised index taking effect on September 21, 2026.
The development has been viewed by market analysts as potentially significant for the visibility of Nigerian equities among international investors, although index inclusion does not automatically translate into foreign capital inflows.
The eventual impact depends on factors including index weights, liquidity and investor appetite.
The International Monetary Fund provides some support for Otedola’s assessment of improved macroeconomic conditions, while also highlighting significant challenges.
In its June 2026 Article IV assessment, the IMF said reforms implemented over the preceding three years—including the removal of fuel subsidies, tighter monetary policy and foreign-exchange liberalisation—had strengthened macroeconomic stability, rebuilt external buffers and improved the functioning of the forex market.
The Fund estimated Nigeria’s real GDP growth at 4 per cent in 2025 and projected 4.1 per cent growth for 2026.
However, the IMF cautioned that improved macroeconomic indicators had not eliminated pressures facing households. It estimated that poverty had reached 63 per cent under the national poverty line and that 27 million Nigerians faced food insecurity in late 2025. It also warned that higher food and fuel prices could intensify those pressures.
An IMF analysis published in June also found that inflation persistence had declined following the forex forms, suggesting that the economy had become more responsive to monetary policy, although inflation remained a major concern.
For Otedola, however, the developments in financial markets, foreign exchange and investment confidence represent evidence that the government’s reform agenda is moving the economy in the right direction.