
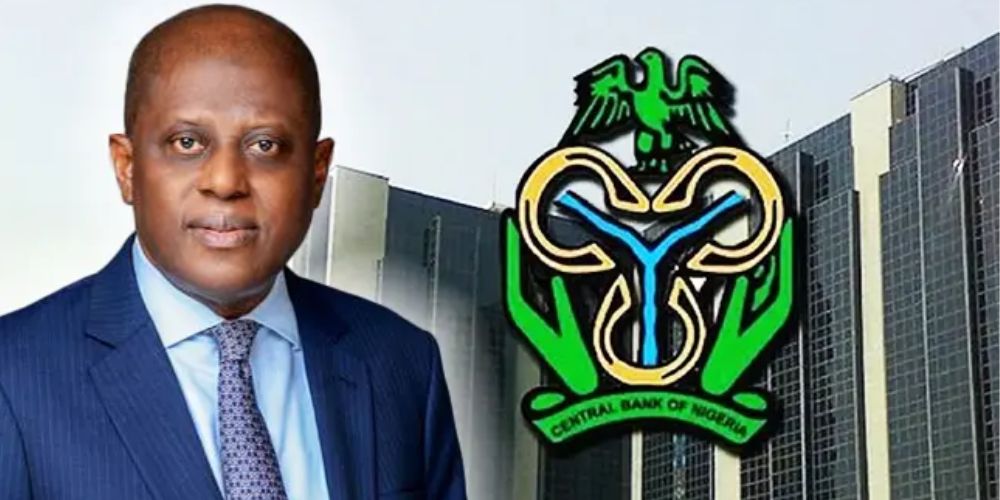
Three years into Olayemi Cardoso’s tenure as Governor of the Central Bank of Nigeria, the apex bank’s reform programme has produced significant changes in the country’s foreign exchange market, external reserves and banking sector.
However, the improvements in macroeconomic and financial indicators have yet to fully translate into cheaper credit, stronger productive-sector growth and improved living conditions for businesses and households.
Cardoso assumed office on September 22, 2023, amid severe pressure on Nigeria’s economy. Inflation stood at 26.72 per cent, the Monetary Policy Rate was 18.75 per cent and gross external reserves were about $33.2 billion, according to a review of the CBN’s position at the time. The foreign exchange market was also characterised by limited liquidity and significant distortions.
Three years later, gross external reserves have risen above $55 billion, while the CBN says its reforms have improved transparency and liquidity in the foreign exchange market. Net foreign exchange reserves also increased substantially, reaching $34.8 billion at the end of 2025 from $3.99 billion two years earlier.
A central feature of Cardoso’s approach has been a shift towards conventional monetary policy and away from some of the CBN’s previous development-finance interventions.
The apex bank has focused more heavily on price stability, liquidity management, foreign exchange market reforms and financial-sector stability. It has also pursued the recapitalisation of commercial banks, with lenders required to strengthen their capital bases to support a larger and more resilient financial system.
The foreign exchange reforms have been among the most visible changes. The CBN moved to reduce multiple exchange-rate distortions and improve price discovery, while measures were introduced to increase transparency in the market and strengthen confidence in the naira.
The changes have also received external recognition. S&P Global Ratings upgraded Nigeria’s long-term foreign and local currency sovereign ratings from ‘B-’ to ‘B’ in 2026, citing improvements in the country’s external position, foreign exchange liquidity, fiscal revenues and ongoing structural reforms. The agency specifically identified the liberalisation of the foreign exchange market as one of the factors supporting improved access to foreign currency and investor confidence.
Yet the reform story is not without significant challenges.
The naira remains considerably weaker against the dollar than it was when Cardoso took office, while the cost of borrowing remains high. Although the CBN reduced its Monetary Policy Rate to 23 per cent at its September 2026 meeting, it retained the Cash Reserve Requirement for deposit money banks at 45 per cent.
The September rate cut marked a shift from the prolonged monetary tightening of the preceding years, but its impact on lending rates and economic activity will depend on how quickly monetary easing is transmitted through the banking system.
For businesses, particularly manufacturers, farmers and small and medium-sized enterprises, the critical question is whether stronger bank balance sheets and improving macroeconomic stability will eventually translate into affordable financing.
Nigeria’s broader economic performance has shown signs of improvement. Real GDP grew by 4.43 per cent in the second quarter of 2026, up from 3.89 per cent in the first quarter, while business activity remained in expansion territory. However, manufacturing growth has continued to lag some of the broader improvements, underscoring the gap between macroeconomic stability and conditions in the productive economy.
That gap is increasingly becoming the central test of the CBN’s reforms.
Higher reserves strengthen the country’s external buffers, but they do not automatically increase household incomes. A more transparent foreign exchange market can improve access to dollars, but it does not by itself guarantee lower production costs. Similarly, stronger banks do not necessarily mean cheaper loans for businesses.
The CBN therefore faces the challenge of preserving the gains made in monetary and financial stability while ensuring that those gains reach the wider economy.
The September reduction in the policy rate suggests that the monetary policy environment may be entering a different phase. After years of prioritising inflation control, exchange-rate stability and rebuilding confidence, attention is increasingly shifting towards how the financial system can support investment and productive activity without reigniting inflationary pressures.
For Cardoso, the next phase may therefore be judged less by the size of the CBN’s reserves or the number of regulatory reforms implemented and more by whether businesses can access credit at sustainable rates, private investment strengthens, productivity improves and households begin to feel the benefits of greater macroeconomic stability.
Three years into the reform programme, the CBN has made measurable progress in rebuilding financial buffers and reshaping monetary and foreign exchange policy. The harder task now is demonstrating that those gains can move beyond financial and macroeconomic indicators into stronger economic activity, employment, investment and household welfare.